

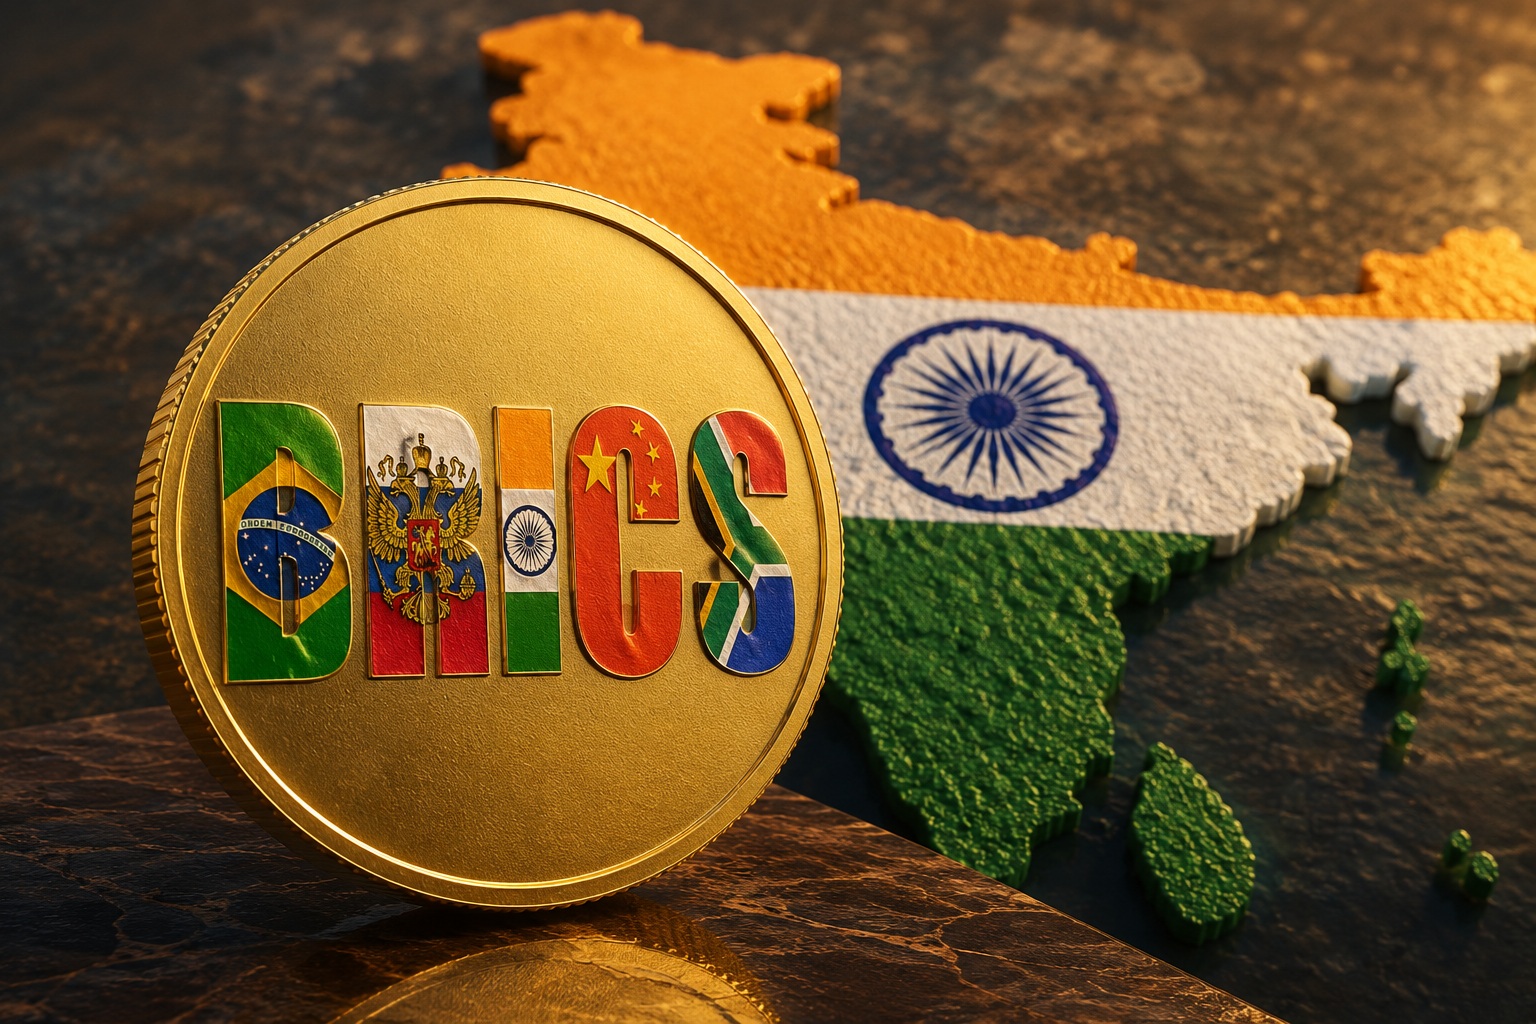
- India, the host of the next BRICS summit, plans to present its proposal for a stablecoin tailored for cross-border trades among members of the international cooperation.
- Information suggests it may be exploring a multi-asset stablecoin rather than proceeding with the CBDC design the organization floated around earlier.
Over the years, the BRICS alliance has been teasing the creation of a common currency to untether their cross-border transactions from the US dollar. Among the things considered was a Central Bank Digital Currency (CBDC) pegged to the yuan. Others weighed pegging it to tokenized gold for neutrality.
Another Round of Talks on a Common BRICS Currency
The international cooperation comprising 11 member countries will hold its annual summit on September 12-13 in New Delhi, India. Prime Minister Narendra Modi, the council’s chairman this year, is reportedly preparing to continue talks on creating a common currency that BRICS nations and partners could use for cross-border trade.
To date, BRICS members include:
- Brazil
- Russia
- India
- China
- South Africa
- Egypt
- Ethiopia
- Iran
- United Arab Emirates (UAE)
- Indonesia
- Saudi Arabia
The organization’s partner countries include:
- Belarus
- Bolivia
- Kazakhstan
- Cuba
- Malaysia
- Nigeria
- Thailand
- Uganda
- Uzbekistan
- Vietnam
Sources familiar with the matter claimed that the host plans to explore a stablecoin model rather than a CBDC framework. However, official details are scarce, so anything about it at this point is speculative.
Potential Adoption of a Multi-Asset BRICS Stablecoin
The BRICS choosing a multi-asset stablecoin or tokenized design will offer a more neutral, flexible, and technologically pragmatic approach to solving the inherent friction in international payments across BRICS and its partners. These include high foreign exchange fees, long settlement processes, and exposure to third-party intermediary risks.
Meanwhile, opting for a multi-asset stablecoin model instead of a CBDC would allow BRICS members to preserve their monetary sovereignty. It eliminates the need to give up authority to a single supra-national central bank or surrender domestic monetary policy control, which have been major sticking points in earlier unified-currency discussions.
IMF Warning on Stablecoins
Dan Katz, First Deputy Managing Director of the International Monetary Fund (IMF), believes that increased competition in retail digital payments from stablecoins offers advantages in cross-border payments by lowering remittance costs. He highlighted that the trend is already underway, and the growing integration of artificial intelligence (AI) may accelerate adoption.
However, Katz echoed the IMF’s earlier warnings, including those from the Bank for International Settlements (BIS), that stablecoins could trigger currency substitution. This could be prevalent in emerging economies.
The IMF official emphasized that strong macro fundamentals and clear policies serve as the best defense against currency substitution amid the rising adoption of stablecoins.